TrendForce projects that global notebook shipments could decline by a high-single-digit percentage in 2027, depending on how manufacturers respond to rising component costs. Here are the details.
’Brands [to] face difficult trade-offs’
In a report released this week, TrendForce projects that global notebook shipments will decline in 2027, with the drop ranging from low- to high-single digits, depending on how manufacturers respond to rising costs.
TrendForce says the impact will depend on how much of the rising component costs manufacturers pass on to consumers through higher retail prices, rather than absorbing them at the expense of their profit margins.
From the report:
TrendForce says that notebook shipments in 2026 were supported by factors such as improved CPU availability, early purchasing by manufacturers, and replacement demand brought forward from later periods.
The report notes that 68% of the bill of materials for an unnamed “mainstream notebook with a manufacturer’s suggested retail price of US$900” was made up of CPU, DRAM, and SSD costs in the third quarter of 2026.
It adds that next year, if component costs keep rising, brands will likely have to choose between raising retail prices and risking weaker demand, absorbing the increases at the expense of gross margins, or reducing specifications, potentially making their products less competitive.
TrendForce says that DRAM supply is “likely to stay tight” next year thanks to AI-related demand, “while PC DRAM faces the risk of limited supply growth.” On the flip side, it expects NAND Flash supply constraints to “ease in the second half of 2027 with new capacity coming online. “
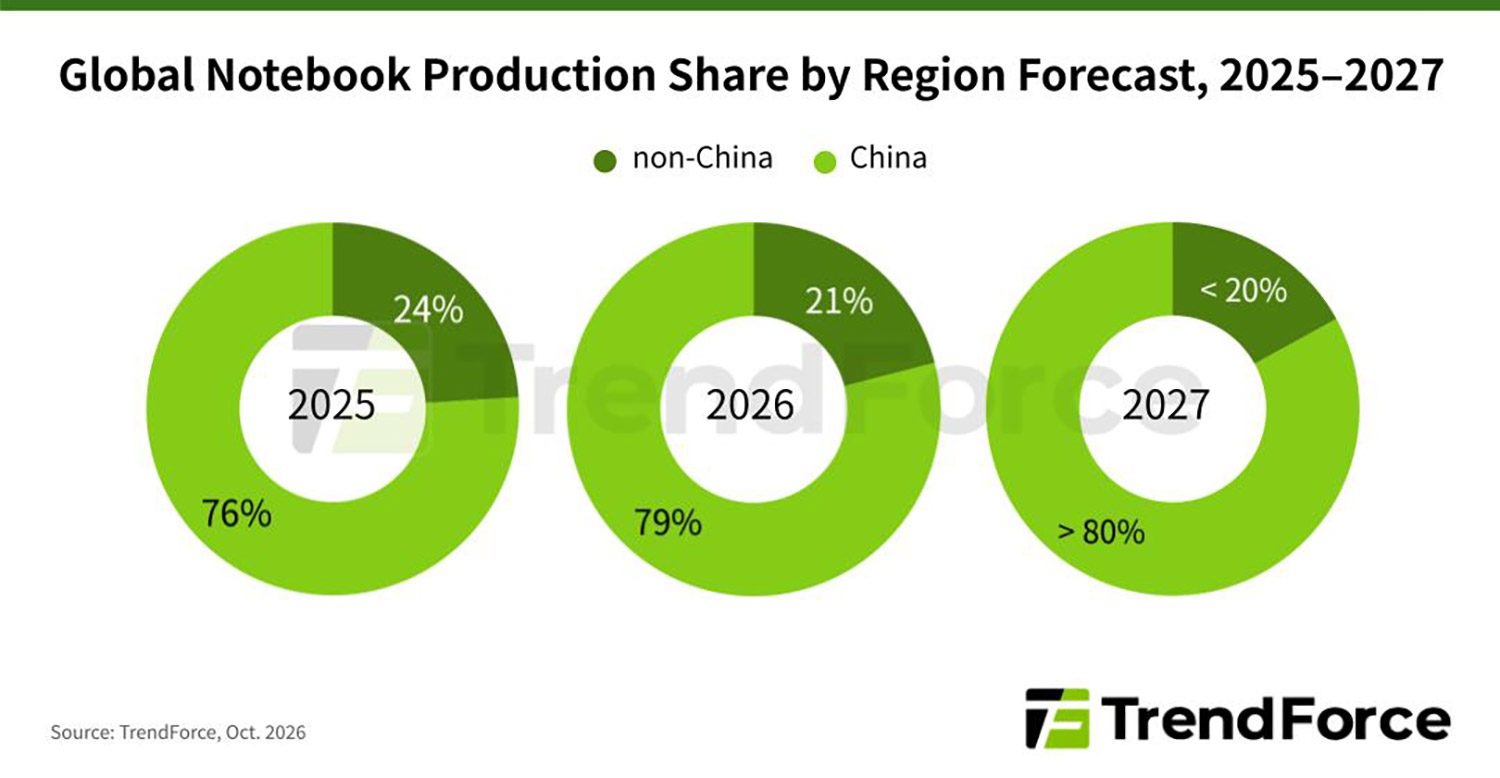
Finally, the report notes that if tariff pressures don’t increase further, manufacturers could move some notebook production back to China to reduce costs. TrendForce estimates that China’s share of global notebook production will rise from 76% in 2025 to 79% in 2026, potentially exceeding 80% in 2027.
To read TrendForce’s full report, follow this link.
